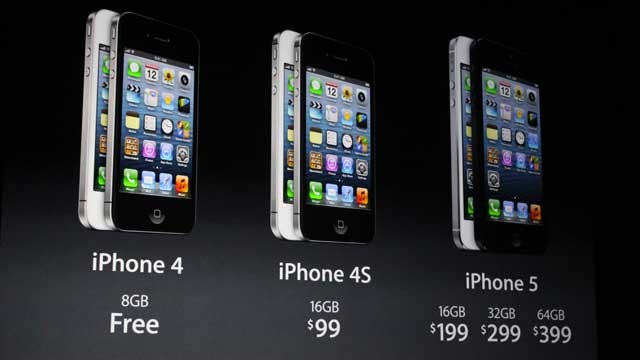
T-Mobile is probably the earliest to report Q1 2013 numbers, over a month ahead of the May 8, 2013 Deutsche Telekom formal release date. Only after 4 days since the first quarter closed, they reported some specific subscriber and churn data through their press release.
Here's a full look (2012 and Q1 2013) at the metrics on a table (click on the graphic for a bigger view).

Why So Early?
T-Mobile needs to show that its strategy is succeeding. A key part of the 2013 goal/strategy is to stabilize the postpaid subscriber base. By all accounts, Q1 2013 is going well in the ~ 60% range decrease in postpaid losses sequentially and year-over-year. Though the company is still bleeding postpaid subs, the trend is positive. Q2 will be a crucial quarter as the iPhone goes on sale and the marketing to push AT&T switchers increase. The trajectory looks good and the question for T-Mobile is which quarter the company crosses a positive net addition.
Wholesale to the Rescue
The pickup in MVNO and machine-to-machine subscribers have been saving the company's bacon for several quarters. Both categories account for 576K net adds. The irony is that the MVNO partners such as Tracfone's StraightTalk and SimpleMobile are vying for the same price sensitive prepaid base is in the running for. However this is likely to be a similar prepaid segmentation strategy that Sprint is employing. When MetroPCS is complete, there will likely be additional rejiggering of the strategy.
Missing Data
We'll all have to wait for the financial numbers to be released in May. Aside from overall revenue and EBITDA margins, ARPU will be somethings that I'm looking for include the direction of CPGA and ARPU for postpaid and prepaid.
Here's a full look (2012 and Q1 2013) at the metrics on a table (click on the graphic for a bigger view).

Why So Early?
T-Mobile needs to show that its strategy is succeeding. A key part of the 2013 goal/strategy is to stabilize the postpaid subscriber base. By all accounts, Q1 2013 is going well in the ~ 60% range decrease in postpaid losses sequentially and year-over-year. Though the company is still bleeding postpaid subs, the trend is positive. Q2 will be a crucial quarter as the iPhone goes on sale and the marketing to push AT&T switchers increase. The trajectory looks good and the question for T-Mobile is which quarter the company crosses a positive net addition.
Wholesale to the Rescue
The pickup in MVNO and machine-to-machine subscribers have been saving the company's bacon for several quarters. Both categories account for 576K net adds. The irony is that the MVNO partners such as Tracfone's StraightTalk and SimpleMobile are vying for the same price sensitive prepaid base is in the running for. However this is likely to be a similar prepaid segmentation strategy that Sprint is employing. When MetroPCS is complete, there will likely be additional rejiggering of the strategy.
Missing Data
We'll all have to wait for the financial numbers to be released in May. Aside from overall revenue and EBITDA margins, ARPU will be somethings that I'm looking for include the direction of CPGA and ARPU for postpaid and prepaid.