Quintel Blogger theme

A free Premium Blogger theme.

Showing posts with label Leap Wireless. Show all posts

Tuesday, July 16, 2013

AWS Spectrum Maps - Before and After: AT&T-Leap Buyout

In yesterday's post, we saw the results of a combined entity spectrum depth map that displayed the 700MHz, Cellular, PCS and AWS bands.  However, one of the points I brought up was AT&T staying in the AWS spectrum game for LTE capacity fill in (to 700) and to position itself from an AWS LTE roaming standpoint. In this post, we are fortunate to show the AWS holdings for Leap and AT&T. 

Leap AWS spectrum

AT&T AWS spectrum

Combined AT&T-Leap AWS spectrum


What have we concluded? Specifically, the AWS national footprint still far from filled as evidenced by the white on the map. Once AWS LTE roaming happens, AT&T has the option to fill those areas, if necessary.

Despite the AWS gaps, we can see that Leap will strength AT&T LTE in specific markets such as:
  • (West) Seattle, central California, San Diego, Salt Lake City, Denver
  • (Southwest) Las Vegas, Phoenix, Tuscon, Sante Fe, El Paso
  • (Midwest) Kansas City, Omaha, Chicago, Milwaukee, St. Louis, Cincinnati, Louisville, Nashville
  • (South-ish) San Antonio, Ok City, New Orleans, Little Rock, Memphis, Hashville   
  • (Mid-Atlantic) Baltimore, Philadelphia, Washington, DC, Richmond, Charlotte, Raleigh, Columbia
  • (East-ish) Buffalo, Pittsburgh
Again, the combined AT&T-Leap spectrum depth map (note this excludes WCS spectrum)


Thanks to Mosaik for their output.

Monday, July 15, 2013

The AT&T-Leap Spectrum Depth (A Map View)

Spectrum is indeed a prime factor in any wireless carrier acquisition. Spectrum maps play an important role in understanding deal motivation and what the resulting merged entities' national spectrum depth looks like.

The Leap spectrum view:
Though Leap's spectrum (mainly PCS and AWS (the 700 in Chicago is for sale)) goes beyond their operating regional markets, the company's business model focuses in on densely populated markets. 

The AT&T spectrum view:
The combined AT&T-Leap spectrum view:


With the Leap spectrum, AT&T is strengthened in some heavily contested markets including, the Mid-Atlantic, central California, Las Vegas (better AT&T service at CTIA?), Denver, KC (Sprint's backyard), St. Louis (Sprint's newest market acquisition from US Cellular), and Northwest (Seattle - T-Mobile's backyard). Of course, the big question is will spectrum need to be divested?  The Department of Justice uses the Herfindahl-Hirschman Index (HHI) to measure market concentration for purposes of antitrust enforcement.  

Note: Thanks to Mosaik for the use of their MapElements output. 

Sunday, July 14, 2013

Bullet Point Analysis: The AT&T-Leap Buyout


What is it?


AT&T is buying prepaid player Leap Wireless for $15 per share in cash. Under the terms of the agreement, AT&T will acquire all of Leap’s stock and wireless properties, including licenses, network assets, retail stores and approximately 5 million subscribers. AT&T expects the transaction to complete in 6-9 months (1H 2014).

What is in it for Leap?


  • For shareholders and management, they can exit the cut throat prepaid business with money. Leap and similar regional prepaid player, MetroPCS, had once enjoyed strong growth until a couple of years ago. National competitors and prepaid MVNOs ate into their marketshare and growth. T-Mobile's acquisition of MetroPCS that closed in May 2013 logically put a brighter spot light on Leap. 
  • For Leap operations, the Cricket brand expands its geographical reach beyond Leap's limited regional footprint and can go head-to-head against MetroPCS and can tap into AT&T's distribution resources.
  • For the Leap network, it has a clearer LTE path. Operating CDMA (96M POPs) and LTE (21M POPs) in the same limited AWS spectrum bands doesn't work well.   

What is in it for AT&T?


Spectrum:  

  • Complementary PCS and AWS bands covering 137M POPs, some of AWS is not in service (41M POPs).
  • Proceeds from the Leap 700 A Block spectrum goes into the deal calculus.


Subscribers and Doors: 
  • Leap has 5 million prepaid subscribers but the company has been trying to right itself after steady customer losses that began in Q2 2012. AT&T increases its prepaid customer base to roughly 12 million, roughly 11% of the AT&T total subscriber base.
  • Leap's distribution channel numbers a little less than 9,000 doors.  
  • Commentary: Leap's business needs a turnaround that Leap's management has been trying to accomplish for more than a year. In that time, Leap lost about 900K customers. Leap's distribution also slimmed down from over 11K doors in a bid to focus customer acquisition.  AT&T's own branded prepaid is not growing. The launch of the Aio brand in May allows for the company to enter the prepaid market aggressively without diminishing the AT&T brand. Now that Leap joins the AT&T prepaid fight, the strategy is shaping up to match the segmentation strategy pioneered by Sprint (Boost, Virgin, Assurance) and Tracfone (Tracfone, StraightTalk, Net10, Simple Mobile, PagePlus, and Safelink). T-Mobile also joins in the prepaid segmentation fight with its own GoSmart and MetroPCS).  All this Tier-1 competition and the plethora of MVNOs out there vying for the prepaid share of wallet will make for thin margins.  
Strategic Positioning:

Keeping T-Mobile Away: There are many who say this is a spectrum deal. That is true that additional PCS and AWS spectrum enhances the AT&T network, I argue that a large element is to neutralize a growing T-Mobile threat. Fresh off the May close of MetroPCS, T-Mobile supplemented its AWS spectrum with a $308M deal with US Cellular at the end of June.  
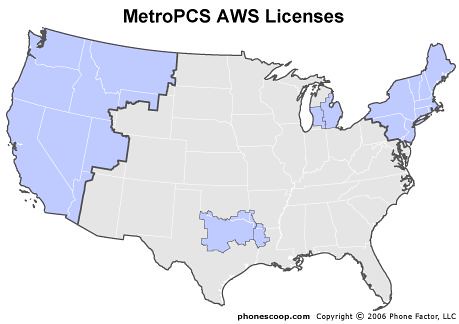
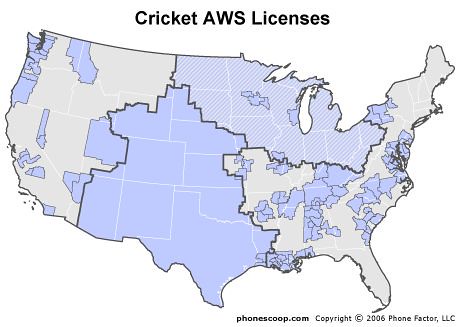
    To understand it roughly, rewind back to the ongoing speculation that a then independent MetroPCS and Leap were a perfect fit since both had the same prepaid business models and did not compete against each other for the most part. The results of the 2006 AWS auction (see graphics below) helped fuel this speculation as the AWS  MetroPCS and Leap spectrum fit provided an uncannily perfectly complement. Time has passed and some AWS licenses changed hands. 


      Graphics from Phonescoop.com
      But with the AT&T-T-Mobile merger breakup, T-Mobile received some AWS licenses and in 2012, Leap and T-Mobile traded some licenses. While the T-Mobile-MetroPCS coverage map looks empty in some areas of the country, that is not to say that the company lacks spectrum in those areas. 
      As seen in the spectrum holdings graphic, the company does indeed have spectrum nationally and can expand if so desired.  


      With the June purchase of Mississippi Valley AWS spectrum from US Cellular (Barat) Wireless) and a future rumored purchase of Leap, the T-Mobile AWS portfolio would be formidable. Aside from T-Mobile, archrival Verizon Wireless' SpectrumCo AWS deal completed in August 2012 and building out this AWS to add LTE network capacity.  


      This competitive landscape would put AT&T in an AWS coverage disadvantage relative to T-Mobile and Verizon Wireless. Therefore, AT&T needed to stay in the AWS LTE game and keep T-Mobile from growing a stronger AWS portfolio. For AT&T, AWS will not only to serve to add LTE capacity customers but also tap into future AWS LTE roaming revenue. T-Mobile, AT&T and Verizon Wireless are logical future roaming partners.  


      Which companies will feel the most impact?

      • For T-Mobile, with Leap as a unit of AT&T, its MetroPCS geographic expansion will be challenged by AT&T's resources.  T-Mobile seemingly has a year or two lead as it is integrating MetroPCS and working on migrating the CDMA base to HSPA+/LTE but the stated goal of 2015.
      • Sprint will lose 3G data wholesale revenue from the agreement forged in August 2010 that expires in Dec 2015. But now Sprint (Clearwire's owner) loses another wholesale arrangement that Clearwire announced in March 2012 though nothing really started.  It's clear now that Sprint's prepaid segmentation strategy was the correct in the long run but Aio Wireless and Cricket are going up against Virgin, Boost, Assurance, respectively. Cricket's logical national (or specific target market) expansion may spell trouble. 
      • Verizon Wireless now sees a stronger AT&T rival with new found AWS and PCS spectrum from Leap. In the long term, it needs additional spectrum to thwart impending capacity brought on with WCS and Channel 55 (700 from Qualcomm) frequencies. In terms of prepaid, its branded prepaid is holding its own but without any flanker brands, competitors will take almost all the future prepaid growth.
      • In infrastructure, AT&T LTE equipment suppliers, Alcatel and Ericsson now have more of an order pipeline than before.

      Last Word

      • The biggest question in this deal is whether the acquisition will pass regulatory hurdles. The sting of the failure to acquire T-Mobile is still fresh in everyone's minds. Like any major deal, it should have been gamed out by M&A internal and external resources taking into account the regulatory environment before it makes the light of day. 
      • If regulatory hurdles are overcome, what conditions will there be? AT&T has proactively said that the Chicago 700 MHz A Block will be sold. (It doesn't like the A block anyway). Will the company need to divest in other markets (planned or unplanned)? 

      Monday, March 11, 2013

      4Q2012 Prepaid Carrier Trends – Be Warned – It’s A Long One

      Now that the Q4 2012 earnings are done, let’s look at the segment that had been driving a lot of the wireless growth in the past few years – prepaid. Rewind back to 2007/2008, Leap and MetroPCS were strongly acquiring subscribers with their unlimited propositions. The subsequent years saw similar flat rate introductions from the likes of Boost, Virgin Mobile, Tracfone’s StraightTalk and NET10. With the pressure from the monthly prepaid plans, Tier 1 carriers Verizon Wireless, AT&T and T-Mobile also joined the mix. The commonality in competition is for the high-value user. The traditional pay-as-you-go (PAYG) user’s contribution is far less. These users range from ‘glove box’ (low use) to moderate users. They also tend to be highly price sensitive and have a higher churn profile. The opposite is true to monthly plan users. These users while also price sensitive are heavier users and are fine with a flat rate model for predictability. They often have a lower churn profile relative to the PAYG user. That’s not to say they’re in the postpaid sub 2% churn territory. But for the prepaid segment, these monthly users are lower churn. 

      Smartphones have been appearing in the prepaid segment for the last two years. While the companies want to offer the same capabilities as the postpaid segment, the prepaid model calls for low to no subsidies on devices. Of course companies strive to find low cost providers (e.g., Huawei and ZTE) to fill that niche and to leverage price against existing suppliers (e.g., Samsung, LG, Kyocera, HTC, etc.). The goal of course is to drop the smartphone price so that buyer can perceive that they’re affordable. However, prepaid providers walk a fine line for inexpensive devices because if a device is perceived as almost a throwaway, the likelihood of churn increases. For those reasons, expensive halo devices like a Samsung Galaxy S3 or the Apple iPhone keep the carrier sticky. 
      With this as a backdrop, let’s look at how the players fared? Purely on net addition numbers, we can see that the regional unlimited players that ruled the day back in 2007/2008 are in trouble with Leap Wireless in the poorest shape with over 300K in subscriber losses. In Leap’s earnings call they noted that they are de-emphasizing their pay-as-you-go and mobile broadband business. There is logic in this as mobile broadband users eat more bandwidth (leaving less for monthly users) and PAYG are less revenue generating. MetroPCS though with less subscriber loss follows the same loss trend that has plagued Leap for many quarters. The company claims that they’re de-emphasizing CDMA growth but this tactic has resulted in an overall 5% loss in the base. This meshes with the long term strategy anyway once T-Mobile integrates and eventual use the 1900 CDMA to convert to 1900 HSPA+. By contrast, Tracfone’s net additions are by far the most impressive. The company buys wholesale from many carriers and has a large mix of PAYG and a growing base of monthly users. Presumably StraightTalk is doing well for the company as evident in ARPU. Several years ago, Tracfone ARPU was 10. In Q4 2011, it was 16 and in Q4 2012, it is now 18. APRU just doesn’t jump like this by growing a purely PAYG product. 


      While Verizon Wireless had a tremendous Q4 in the postpaid side with over 2.1M net adds, the positive prepaid numbers indicate their competitiveness. Despite a down from a year ago and the previous quarter, it speaks to their premium brand messaging and perhaps a new November double data plan promotion. This is pretty decent for a predominately postpaid company. AT&T on the other hand is on a steeper downward slide. In Q3 2012, the company added 77,000 users with those gains erased with the 166K lost in Q4. AT&T is still a postpaid company with prepaid making up around 7% of the total subs. It will be interesting to see which way the direction turns for AT&T in Q1 2013. Another predominately postpaid carrier doing well in prepaid is US Cellular. Though the regional carrier continues to shed postpaid subscribers, the new U Prepaid plans that it has partnered with Alltel may be helping the cause. 

      Moving onto the rest of the carriers, Sprint’s prepaid numbers have been down relative to previous quarters because the Assurance brand that had been driving huge subscriber count has been slowed due to FCC’s revamping of the subsidized Lifeline program in 2012. The company has already warned of a 1.2-1.3M subscriber loss possibly in Q2 2013 due to the revamping of rules. Regardless, the company indicated that the Boost and Virgin Mobile brands have contributed to the positive numbers. At the same time, the company is actively trying to migrate older Boost iDEN users off ahead of the iDEN network decommissioning. Finally, T-Mobile’s prepaid business is offsetting continued losses (550K) on the postpaid side. Again the above numbers are branded prepaid. T-Mobile counts MVNO (wholesale) net additions as prepaid as well. Branded prepaid at end of year 2012 represented 17% of the overall T-Mobile base. Looking ahead with the combination of MetroPCS’ prepaid subs, branded prepaid will transform to 45% of T-Mobile’s subscriber count. Given the higher churn profile of prepaid and lower revenue, it’ll looks challenging for future higher revenue contribution. But that’s months away…. Q1 2012 typically continues Q4 sales momentum. We’ll visit that to see what develops.

      Thursday, March 7, 2013

      US 4Q2012 Carrier Results - Google Hangout with RCR Wireless

      Dan Meyer, Editor in Chief of RCR Wireless asked me to discuss Q4 2012 carrier results and some thoughts on some future direction.


      Monday, January 7, 2013

      MetroPCS Q4 and 2012 Results - Ouch

      MetroPCS released their Q4 2012 and year to date 2012 results ahead of the Q4 earnings call later in the month. What stands out is the surprise subscriber loss over the year. 


      With over 93K subs lost in what is supposed to be a hot Q4 holiday selling season,  the results suggest that the prepaid sector is as cut throat and competitive as ever. The result of these losses invariably is a function of its gross additions.  The simple theory goes, if you have a good distribution and acquisition network, you can help offset the subscriber losses and in an optimal scenario, come out ahead.

      MetroPCS' gross additions were also down in Q4 and end of year compared to 2011.  Churn is down a small bit at 0.1% or 10 basis points in financial speak. It's a small win.  There are other metrics that can help tell the story of what's going on such as EBITDA/OIBIDA margin, ARPU, CPU and CPGA but we'll have to wait on that.  While this may look bad, one can give MetroPCS the benefit of a sliver of doubt assuming that they could be letting go of low-value or high-risk users for more profitable customers.

      Yet the prepaid sector is very competitive with many similar offerings from Tier 1 competitors (Verizon Wireless, T-Mobile, AT&T, and Sprint prepaid brands Boost Mobile and Virgin Mobile) and MVNOs such as Tracfone's Straight Talk and Net10.  Another worry may be any hint of distributor apathy ahead of the mid-2013 T-Mobile-MetroPCS transaction. While T-Mobile intends to retain the MetroPCS brand, MetroPCS better figure out how to reverse subscriber losses before the deal is consummated.

      Monday, November 19, 2012

      Verizon Wireless Double Data Comes to a the $80 Prepaid Smartphone Plan

      Verizon Wireless seems to be building up to drive Q4 2012 and Q1 2012 prepaid net additions.   Coming off a decent prepaid Q3 with 228K net additions, the prepaid group looks to better 2011 Q4's 250K net additions.  How does the company get there? 

      Given the smartphone adoption trends, the company wants to take advantage of this in the Q4 holiday selling period. To accomplish interest, Verizon Wireless has taken a page from its postpaid double data promotion it ran in 2011 and early 2012.  The plan under the limelight is the Prepaid $80 Smartphone plan that normal provides 1 GB of data along with unlimited talk and text. This is already competitive with postpaid but now with a 2GB.


      Here are the plan terms in minutaie but the highlighted points are the important ones:

      • For a limited time only, customers who purchase the Prepaid $80 Smartphone plan will enjoy 2GB of data for the price of 1GB when they purchase and activate a new Smartphone between 11/18/2012 through 1/31/2013.
      • Unlimited Talk, Text & 2GB Data Plan includes unlimited domestic calls only, texting* to anyone on any network in the U.S. and participating carriers in Canada, Mexico, and Puerto Rico and 1GB Data.
      • Purchases and activations on the Unlimited Talk, Unlimited Text & 2GB Data plan will receive 2GB as long as the plan service remains active.
      • The Unlimited Talk, Unlimited Text & 2GB Data plan will not be available after 1/31/2013. Any activation on or after February 1, 2013 will not receive the promotional benefits.
      • If you have a sufficient balance for your monthly access, enjoy the benefits of your calling plan. If you don't have enough funds to cover the monthly access, you will be charged 25¢ per minute, 20¢ per text, 25¢ per picture or video messaging sent (per recipient) and received and 5¢ per MB.
      • 1GB Data Package – An optional data overage package is available for $20 for customers who have reached 100MB or less remaining on the 2GB data allotment. An optional data overage package for prepaid customers is not available for purchase at the point of sale. Customers can add the 1GB data package through the IVR, My Verizon Mobile and My Verizon online once 100MB or less remaining of the 2GB data allotment.

      Target Customer Segment

      Value-seeking smartphone customers who want the Verizon Wireless network. 

      Pros
      - Continue to drive prepaid net additions 
      - Keep filling the 3G network with high-value users.
      - Better than a postpaid deal, addresses the postpaid value switchers
      - Double data for free and a limited time offer has an excellent track record at Verizon Wireless. 
      - Users get to keep the plan as long as they keep their plan active. 

      Cons
      - Only 3G smartphones, no latest and greatest LTE smartphones
      - There are less expensive similar options over at all you can eat competitors Boost Mobile, T-Mobile, MetroPCS (even with LTE) and Leap.

      Thinking about the 4G Coverage POP/Market Race - 1


      The latest in the LTE coverage race: Verizon Wireless' latest network statement states that the company has hit 441 LTE markets. AT&T has also announced its expanded 103 LTE markets/150 million POPs covered on top of the overall 285 million POPs on its 4G HSPA+ network.   

      Coverage and then there is coverage

      The POP or population covered and market race is on again for 4G/LTE coverage. Carriers had been battling in this numbers race back when 3G was introduced.  Population covered had been the norm in showing coverage. However, that is just one component of market positioning.  The other one is geography.  From the national map view, Verizon Wireless is pretty much in the driver’s seat with the 2008 Alltel acquisition.  To Verizon Wireless’ credit, the carrier has been effectively exploiting its geographic advantage and is central to the “Why Verizon Wireless?” marketing strategy.  


      Why haven't AT&T and other tier one carriers T-Mobile and Sprint matching geography coverage?  Simplistically, these carriers are more or less taking a population density approach.  They are covering where most people are using their phones. As one carrier analyst relations professional explained in the past, “We’re not going to build a network to cover cows.” There is financial logic to that as capital expenditures are scrutinized by investors.  What’s the return on investment on covering cows?  Does a company really have enough capital to match Verizon Wireless’ geographic coverage? The short answer is yes but some are in better financial shape than others.   In the 3G realm, forging roaming agreements becomes the equalizer.  For example, Sprint got the map coverage to largely with an agreement with Alltel (pre-Verizon Wireless takeover).  


      Leap in another example uses Sprint as its main roaming partner.   


      Therefore, the operational cost of roaming outweighs the capital cost in building a network in specific markets.  Besides, the ability to provide coverage and connection to customers is extremely important in light of the expectation of US national coverage.  This is all fine for 3G networks but as the industry moves to LTE, a different marketing dynamic takes hold which fuels this vicious coverage arms race again.

      The next post the complexities and confusion that 4G and LTE bring…  

      Thursday, November 8, 2012

      T-Mobile USA Q3 2012 - Postpaid Trouble Continues, Reliance on Prepaid

      T-Mobile released their Q3 2012 numbers along with commentary through the Deutsche Telekom parent.  Some of my thoughts ahead of this release were substantiated and some were not.  The US unit earnings slide touches on four areas, two financial and two operational performance metrics. From a broad view, the financial indicators are on a downward trend. Service revenue, earnings revenue and margin are all down.  Let's dissect the two important operational areas - net additions and ARPU. 


      Net Additions: Though there were 160K net additions, the glass half empty side looks at the postpaid losses.  With nearly 500K of postpaid subscriber losses, it's alarming.  The company blames the iPhone 5 as a key element for the decline.  So where are these people going? AT&T had record iPhone 5 activations and Sprint's iPhone 5 with an unlimited data proposition are the likely culprits.  How does the company reverse its postpaid slide?  Q3 2012 represents the ninth quarter  of postpaid losses.  Its shift to promoting Value plans as part of the greater postpaid strategy may help its margins and lower device subsidy costs but really, is it working?  To deflect this, DT Chairman Rene Obermann cited that there are now 1.5 million iPhones running on the T-Mobile USA network. The last iPhone count was 1 million back in June 2011.  Pushing the glass half full view, the prepaid and wholesale business is contributing to the company's growth.  While wholesale should be positive across the industry, the MVNO business is a consistent performer that makes up almost 12% of the customer base.  The machine-to-machine side represents about 9% of the company.  These two areas should be all accounts continue to add to the customer count throughout the quarters. The prepaid additions are on a very good positive slope, beating previous quarter additions handily.  The introduction of the Monthly4G plans that offer alternatives to Boost, MetroPCS and Leap plans.  Going into Q4 and with the company increasing its customer acquisition spend, can T-Mobile sustain a 300K+ net addition run?


      ARPU:  One take away on the postpaid ARPU is that it's going down.  While the chart shows data ARPU increasing, the subscriber base was traditionally more voice centric.  Minutes of use came in at 899 compared to 986 a year earlier.  This follows the industry trend. The quandary for the company is that it will continue to see a decline in overall ARPU as it pushes its value plans. That may be OK if the business case shows that margins are better in the long run. On prepaid ARPU, the $21 mark was flat sequentially. If the higher ARPU bearing Monthly4G plans take hold en masse this should go up slightly. 

      Churn:   Overall and postpaid churn increased for obvious reasons. The postpaid churn went from 2.2% the previous quarter to 2.3%. Closest rival Sprint has turned its churn fortunes around but its highest postpaid churn rate was 2.01%. Verizon Wireless and AT&T are near 1% as a gauge. 

      T-Mobile USA Q3 2012 Highlights - The Five Core Areas

      The T-Mobile USA Q3 earnings release comes in two forms. One is folded in the parent, Deutsche Telekom's overall earnings.  The second is directly through the US unit.  Surprisingly, the expected Five Core Areas of Focus slide that had been a mainstay in the parent's earnings deck didn't make it.  


      However, this was addressed in the US release.   There is no doubt that positive notes will be slotted in any PR/earnings release. Here's what the company had to say and my takeaways in relation to the Q3 earnings news:

      Amazing 4G Services Highlights:

      • T-Mobile continues to advance its $4 billion 4G network modernization plan, which includes installing new advanced equipment that paves the way for the launch of Long Term Evolution (“LTE”) service in 2013.  <<This reinforces the obvious that T-Mobile is spending the necessary money to make it possible for AWS LTE. While the company is aggressive, a 2013 launch is still nebulous. Is it Q1, 1H, 2H? >>
      • Las Vegas and Kansas City were the first cities where T-Mobile customers benefited from the launch of HSPA+ on 1900 PCS spectrum, which delivers enhanced voice and data coverage, as well as faster speeds on unlocked devices such as the iPhone; just yesterday, Washington DC, Baltimore, and Houston also went live.  The Company expects to announce further network strengthening in many additional cities in the coming months.  <<Refarming the PCS spectrum to enable HSPA+ is the foundation for its BYOD (read iPhone switcher - as blatantly stated) strategy. It's tough to fully market speedy iPhone HSPA+ service when the national network isn't there.  When it gets there, the company will certainly make a big splash.>>  
      • In the third quarter of 2012, T-Mobile completed the transaction announced in June 2012 with Verizon Wireless for the purchase and exchange of AWS spectrum licenses in 218 markets across the U.S.  This transaction improved T-Mobile’s spectrum position in 15 of the top 25 markets nationwide. <<Getting more AWS spectrum allows the company to increase its capacity to continue its unlimited data proposition.  An unknown is whether the additional spectrum may be shifted to increase T-Mobile's long term LTE data throughput speed as a marketing differentiation.   With an LTE-Advanced capable network, that's certainly possible to achieve.>> 
      • T-Mobile continued to expand its compelling 4G smartphone portfolio, including adding more devices under the popular Samsung Galaxy lineup, such as the Samsung Galaxy Note 2, and announcing the upcoming availability of two Windows Phone 8 smartphones, including the exclusive Nokia Lumia 810. <<This is a necessary PR item - to continue to show that new and cool halo devices are coming into the portfolio.  In theory, these should be the halo devices being pushed in the Q4 holiday selling season.>>

      Value Leader Highlights:
      • T-Mobile is a champion of “bring your own device (BYOD)” wireless, with affordable value plans that separate the cost of wireless service from the purchase of a new phone. << Value plans are important to court BYOD iPhone users as they get typically a $5 monthly break off 'Classic' subsidized handset plans.  Honestly, this BYOD plan has been around for many years. T-Mobile sees a plus in this since they don't have to subsidize handsets and get better margin from Value customers.  Of course financing new phones continues to be an option for Value plan users. To the customer, it's usually a wash but clearly there are bigger financial benefits for T-Mobile.>>  
      • In early September, T-Mobile launched a new Unlimited Nationwide 4G Data plan that is a key differentiator in the marketplace. <<These prepaid plans provide a compelling alternative to Boost, MetroPCS and Leap plans. With a better national brand, T-Mobile can exploit these plans to take back customers from those rivals.  With 365K branded prepaid net additions in Q3, these plans have to have had an impact in light of MetroPCS' and Leap's Q3 massive net subscriber losses.>>  
      Trusted Brand Highlights:
      • As part of its brand re-launch program, the Company increased investment in advertising to highlight its fast and reliable nationwide 4G network and its blazing fast data speeds in the U.S. <<In the past analyst conferences, T-Mobile and Sprint have always talked about how much their marketing budgets are dwarfed by Verizon Wireless' and AT&T's spend.  Shifting spokeswoman Carly Foulkes from girl next door to woman in control will continue. Honestly, T-Mobile needs to assert its brand to stay relevant in the consumer mindset as Q4 holiday selling begins.  Over the years, we always look forward to what T-Mobile will do for Black Friday. Recall the 'free airline ticket' promotion?>>

       Multi-Segment Player Highlights:
      • In the Business-to-Business (B2B) segment, T-Mobile looks to serve as a trusted communications advisor, helping businesses develop cost-effective, high-value communications programs that meet their business objectives –through bring-your-own-device (BYOD), and mobile device management (MDM) programs as well as attractive international mobility and mobile broadband data plans.  The Company continues to aggressively expand its B2B sales force. << This is a very important area for T-Mobile. As it was consumer-focused for many years, it largely ignored the business space.  Now the company finds itself starting from scratch to build an effective B2B sales force. It's a tough sell as national rivals Sprint, AT&T and Verizon Wireless are very entrenched.  What is T-Mobile's differentiation in this area?  It's not that clear other than the same proposition on the consumer side - value.>>  
      • T-Mobile launched three new Mobile Virtual Network (MVNO) partnerships during the quarter: Spot Mobile, Solavei, and UltraMobile, adding to its existing partnerships with TracFone/SIMPLE Mobile and Roam Mobility. <<MVNOs represent almost  41% of the company's prepaid business and 12% of the customer base. These should have been technically counted as wholesale. >>  
       Challenger Business Model Highlights:
      • The Company continues with its efforts to drive operational efficiencies through the Reinvent program and is on track to achieve $900 million in annual gross cost savings, which the Company has started reinvesting in customer acquisition programs. << The first part of the rather long sentence is about the cost containment is emblematic of every other wireless carrier. But the details on reinvigorating customer acquisition may suggest further marketing spend, whether targeted or more broadly. >>  


      Wednesday, November 7, 2012

      T-Mobile -Thoughts Ahead of the Q3 2012 Earnings Release

      T-Mobile USA is set to release its Q3 earnings and performance metrics on Thursday , November 8th as part of its overall parent's (Deutsche Telekom) Q3 2012 release.  DT's US unit is fresh off an merger/acquisition announcement of MetroPCS in October  and that had grabbed much of the news around the carrier but the Q3 earnings numbers should reveal whether T-Mobile would continue key trends or reverse them.  The company has provided five focus areas throughout previous quarters and many of its Q3 progress points will fit again in these areas.


      Under Amazing 4G Services, we should expect to hear about network progress (LTE buildout) and new halo devices. Under the Value Leader, we should expect to hear about any new services or marketing initiatives. In furthering the Trusted Brand, T-Mobile has been talking about expanding their distribution. For the last two quarters, the company has been putting a lot of effort into opening new 'doors', the first fruits of this may show up in Q3.  With the Multi-Segment Player focus, this is mostly about expanding wholesale (machine to machine/MVNOs) and ramping up the B2B efforts.   Finally the Challenger thrust should roll up cost control and churn containment.  Maybe there will be light shed on acquiring iPhone switchers. However, some performance metrics continue the bellwether of corporate direction. 

      Net Additions:  The trend doesn't look good for the company as its postpaid base continues on a negative trajectory since Q3 2010. On the other hand, T-Mobile's prepaid business is the bright spot in preventing a totally bleak story. The fact that the company has been able to post positive net prepaid additions in an ultra competitive prepaid segment is notable. Throughout the years, prepaid has been on the rise and makes up more of T-Mobile's customer base. In Q2 2010, the prepaid business accounted for about 20% of the base. By Q2 2012, that percentage increased to over 27%.  Q3 looks to increase that percentage.  Switching over to postpaid, the company still needs to reverse the slide.  The unlimited data and plan value story should resonate and pits the company against Sprint's own unlimited data proposition.  How well the company markets to iPhone switching will be a key element in increasing its postpaid pool.
        
      Any increase should signal somewhat to the traction of its expanded distribution strategy.

      Churn:  Looking at prepaid churn, the company is doing a good job in stabilizing that base.  Q3 should continue the downward direction. However, the churn number currently at 6% is very high relative to rivals.  In contrast, Sprint's multi-branded prepaid group posted 3.37% for Q3 while dedicated prepaid plays MetroPCS and Leap are in mid-3% and mid-4%, respectively.  On the postpaid side, the magic threshold for Q3 should be sub 2%. Rival Sprint crossed that mark two quarters ago. T-Mobile remains the only national carrier to be above the 2% postpaid churn mark.

      ARPU: The carrier is also behind in these metrics relative to its national rivals. The downward postpaid ARPU trend is in stark contrast to AT&T, Sprint and Verizon Wireless which has been sloping positively nicely. While AT&T is the postpaid ARPU leader at over $65, Verizon Wireless is T-Mobile's closest ARPU neighbor at $56 in Q2 before they moved to the new ARPA stat. On the prepaid side Sprint remained over the $26 mark in Q3 while regional Leap and MetroPCS are in the 40s.  To move the mark in prepaid, T-Mobile needs to focus on the high-value users. Of course this will be moot in 2013/2014 once MetroPCS starts to get integrated.


      Finally Network: There will undoubtedly be discussion on how well the LTE buildout is progressing. T-Mobile while it pushes its 4G speed (AWS=based HSPA+), it should be stating how the well the PCS refarming is going. This refarming is central to moving ahead with its AWS LTE plans.  The PCS HSPA+ network also serves as the honeypot for additional unlocked GSM iPhone users. Given the jump that other national carriers have in LTE, there should be a mention or reiteration of when T-Mobile expects to launch LTE markets. 


      Tuesday, October 23, 2012

      AT&T Mobility - Thoughts Ahead of the Earnings Release


      AT&T is set to release its earnings and performance metrics, October 24th at 9:00 AM.   Its earnings has followed Verizon in the past and observers cannot help but compare the two.  Each carriers' wireless divisions are reaping the lions share of revenue growth while the landline business units continue to struggle.

      Net Additions:  AT&T does a good job with net additions.  In previous quarters, these numbers had been boosted through the wholesale group.  Its postpaid organic growth is fine but has not had the tidal wave acquisition momentum as Verizon Wireless.  Q3 should be no different as the postpaid and prepaid net adds should fall in line with previous Q3s.  Q3 has usually trended up for the carrier. Wholesale should continue to bring in the lion's share of the net additions.


      Previous Q3 postpaid net additions have been 745K in 2010 and 319K in 2011. With Q2 2012 coming in at 320K, the logic should be to trend up, also given the iPhone 5 factor. The iPhone has helped the carrier attain switchers in the past, what the percentage is for Q3 should be telling. At the height, the iPhone brought in mid-40% figures for activations that were new to AT&T. 


      The prepaid trend is on a worrisome declining trend. Though additions are admirably positive, the trend is reverse to that of Verizon Wireless' prepaid.  Each carrier has a substantial postpaid base to protect to avoid rate plan cannibalization. Each is bleeding somewhat from the unlimited propositions from MetroPCS, Sprint prepaid brands (Virgin Mobile and Boost), Tracfone's Straight Talk and finally Leap's Cricket. A downward trend is obviously a bad thing but any upward trend suggests that AT&T has looked more aggressively at this segment and wants to play more aggressively.

      Churn:  The trend is in a good direction, both overall and postpaid.  Though Verizon Wireless has been the industry leader for many years, AT&T is doing an admirable job in churn.  The magic mark of note in postpaid is when that value dipped below 1% last quarter. 
      Continued downtrends are obviously desired.  As grabbing switchers has always been a big battleground issue, any reports of a upward voluntary churn indicator would raise eyebrows. However with the iPhone as a key anchor and its own reports of record iPhone 5 sales, expectations for postpaid churn should go down and buck previous Q2 trends of a rise/remain flat.

      ARPU (Rather - Postpaid ARPU):    AT&T has been the leader in postpaid ARPU. In Q2, it neared $65. As a gauge, Sprint is closest with <$61 and Verizon Wireless changed the game in Q3 with shifting the conversation to Average Revenue Per Account (ARPA).  However, Verizon Wireless' Q2 postpaid ARPU came in a little over $56. 

      For Q3, AT&T should break $66 and allow the carrier to continue to reign in postpaid ARPU. Also it may be that AT&T will continue to report ARPU as a metric since it wants to continue to tout that leadership role. Since Verizon Wireless is reporting ARPA, the carrier may bring also  offer their own ARPA calculation either this quarter or the next depending on how much pressure the investment community brings to bear.  A likely scenario may be that AT&T will report both ARPU and ARPA but eventually support ARPA-only down the line.  Since ARPU has been pretty standard in calculation and ARPA seemingly is straight forward, every carrier has to buy-in to make it work for the industry.

      EBITDA Margin(The indicator for profitability): Since this figure is a company's indicator for success, it is an important competitive performance metric.  AT&T continues to chase its rival Verizon Wireless but the gap is decent as Verizon Wireless' whopping Q3 50% figure is rather impressive.  For Q2, AT&T came in at 45%, jumping almost 3% from the previous quarter. No doubt that EBITDA should increase but likely less than 50%. 

      Friday, October 19, 2012

      Carrier Q3 2012 Earnings Releases

      The following are the US carrier Q3 2012 earnings release dates:


      Carrier
      Date
      Time (ET)
      Verizon
      Thu, October 18
      8:30 AM
      AT&T
      Wed, October 24
      9:00 AM
      Sprint
      Thu, October 25
      8:00 AM
      Clearwire
      Thu, October 25
      4:40 PM
      MetroPCS
      Tues, October 30
      9:00 AM
      Leap
      Wed, November 7
      11:00 AM
      T-Mobile
      Thu, November 8
      4:00 AM