Now that the Q4 2012 earnings are done, let’s look at the segment that had been driving a lot of the wireless growth in the past few years – prepaid. Rewind back to 2007/2008, Leap and MetroPCS were strongly acquiring subscribers with their unlimited propositions. The subsequent years saw similar flat rate introductions from the likes of Boost, Virgin Mobile, Tracfone’s StraightTalk and NET10. With the pressure from the monthly prepaid plans, Tier 1 carriers Verizon Wireless, AT&T and T-Mobile also joined the mix. The commonality in competition is for the high-value user. The traditional pay-as-you-go (PAYG) user’s contribution is far less. These users range from ‘glove box’ (low use) to moderate users. They also tend to be highly price sensitive and have a higher churn profile. The opposite is true to monthly plan users. These users while also price sensitive are heavier users and are fine with a flat rate model for predictability. They often have a lower churn profile relative to the PAYG user. That’s not to say they’re in the postpaid sub 2% churn territory. But for the prepaid segment, these monthly users are lower churn.
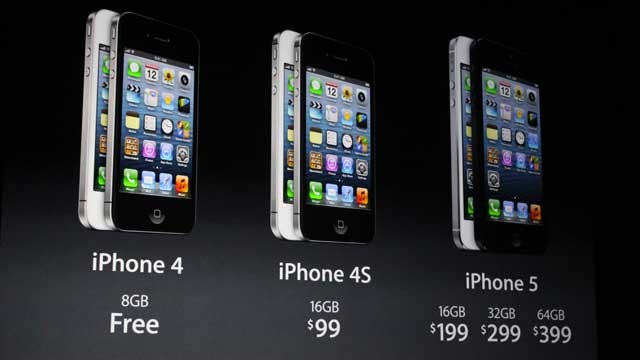
Smartphones have been appearing in the prepaid segment for the last two years. While the companies want to offer the same capabilities as the postpaid segment, the prepaid model calls for low to no subsidies on devices. Of course companies strive to find low cost providers (e.g., Huawei and ZTE) to fill that niche and to leverage price against existing suppliers (e.g., Samsung, LG, Kyocera, HTC, etc.). The goal of course is to drop the smartphone price so that buyer can perceive that they’re affordable. However, prepaid providers walk a fine line for inexpensive devices because if a device is perceived as almost a throwaway, the likelihood of churn increases. For those reasons, expensive halo devices like a Samsung Galaxy S3 or the Apple iPhone keep the carrier sticky.

 With this as a backdrop, let’s look at how the players fared? Purely on net addition numbers, we can see that the regional unlimited players that ruled the day back in 2007/2008 are in trouble with Leap Wireless in the poorest shape with over 300K in subscriber losses. In Leap’s earnings call they noted that they are de-emphasizing their pay-as-you-go and mobile broadband business. There is logic in this as mobile broadband users eat more bandwidth (leaving less for monthly users) and PAYG are less revenue generating. MetroPCS though with less subscriber loss follows the same loss trend that has plagued Leap for many quarters. The company claims that they’re de-emphasizing CDMA growth but this tactic has resulted in an overall 5% loss in the base. This meshes with the long term strategy anyway once T-Mobile integrates and eventual use the 1900 CDMA to convert to 1900 HSPA+. By contrast, Tracfone’s net additions are by far the most impressive. The company buys wholesale from many carriers and has a large mix of PAYG and a growing base of monthly users. Presumably StraightTalk is doing well for the company as evident in ARPU. Several years ago, Tracfone ARPU was 10. In Q4 2011, it was 16 and in Q4 2012, it is now 18. APRU just doesn’t jump like this by growing a purely PAYG product.


While Verizon Wireless had a tremendous Q4 in the postpaid side with over 2.1M net adds, the positive prepaid numbers indicate their competitiveness. Despite a down from a year ago and the previous quarter, it speaks to their premium brand messaging and perhaps a new November double data plan promotion. This is pretty decent for a predominately postpaid company. AT&T on the other hand is on a steeper downward slide. In Q3 2012, the company added 77,000 users with those gains erased with the 166K lost in Q4. AT&T is still a postpaid company with prepaid making up around 7% of the total subs. It will be interesting to see which way the direction turns for AT&T in Q1 2013. Another predominately postpaid carrier doing well in prepaid is US Cellular. Though the regional carrier continues to shed postpaid subscribers, the new U Prepaid plans that it has partnered with Alltel may be helping the cause.
Moving onto the rest of the carriers, Sprint’s prepaid numbers have been down relative to previous quarters because the Assurance brand that had been driving huge subscriber count has been slowed due to FCC’s revamping of the subsidized Lifeline program in 2012. The company has already warned of a 1.2-1.3M subscriber loss possibly in Q2 2013 due to the revamping of rules. Regardless, the company indicated that the Boost and Virgin Mobile brands have contributed to the positive numbers. At the same time, the company is actively trying to migrate older Boost iDEN users off ahead of the iDEN network decommissioning. Finally, T-Mobile’s prepaid business is offsetting continued losses (550K) on the postpaid side. Again the above numbers are branded prepaid. T-Mobile counts MVNO (wholesale) net additions as prepaid as well. Branded prepaid at end of year 2012 represented 17% of the overall T-Mobile base. Looking ahead with the combination of MetroPCS’ prepaid subs, branded prepaid will transform to 45% of T-Mobile’s subscriber count. Given the higher churn profile of prepaid and lower revenue, it’ll looks challenging for future higher revenue contribution. But that’s months away…. Q1 2012 typically continues Q4 sales momentum. We’ll visit that to see what develops.
Smartphones have been appearing in the prepaid segment for the last two years. While the companies want to offer the same capabilities as the postpaid segment, the prepaid model calls for low to no subsidies on devices. Of course companies strive to find low cost providers (e.g., Huawei and ZTE) to fill that niche and to leverage price against existing suppliers (e.g., Samsung, LG, Kyocera, HTC, etc.). The goal of course is to drop the smartphone price so that buyer can perceive that they’re affordable. However, prepaid providers walk a fine line for inexpensive devices because if a device is perceived as almost a throwaway, the likelihood of churn increases. For those reasons, expensive halo devices like a Samsung Galaxy S3 or the Apple iPhone keep the carrier sticky.


While Verizon Wireless had a tremendous Q4 in the postpaid side with over 2.1M net adds, the positive prepaid numbers indicate their competitiveness. Despite a down from a year ago and the previous quarter, it speaks to their premium brand messaging and perhaps a new November double data plan promotion. This is pretty decent for a predominately postpaid company. AT&T on the other hand is on a steeper downward slide. In Q3 2012, the company added 77,000 users with those gains erased with the 166K lost in Q4. AT&T is still a postpaid company with prepaid making up around 7% of the total subs. It will be interesting to see which way the direction turns for AT&T in Q1 2013. Another predominately postpaid carrier doing well in prepaid is US Cellular. Though the regional carrier continues to shed postpaid subscribers, the new U Prepaid plans that it has partnered with Alltel may be helping the cause.
Moving onto the rest of the carriers, Sprint’s prepaid numbers have been down relative to previous quarters because the Assurance brand that had been driving huge subscriber count has been slowed due to FCC’s revamping of the subsidized Lifeline program in 2012. The company has already warned of a 1.2-1.3M subscriber loss possibly in Q2 2013 due to the revamping of rules. Regardless, the company indicated that the Boost and Virgin Mobile brands have contributed to the positive numbers. At the same time, the company is actively trying to migrate older Boost iDEN users off ahead of the iDEN network decommissioning. Finally, T-Mobile’s prepaid business is offsetting continued losses (550K) on the postpaid side. Again the above numbers are branded prepaid. T-Mobile counts MVNO (wholesale) net additions as prepaid as well. Branded prepaid at end of year 2012 represented 17% of the overall T-Mobile base. Looking ahead with the combination of MetroPCS’ prepaid subs, branded prepaid will transform to 45% of T-Mobile’s subscriber count. Given the higher churn profile of prepaid and lower revenue, it’ll looks challenging for future higher revenue contribution. But that’s months away…. Q1 2012 typically continues Q4 sales momentum. We’ll visit that to see what develops.