Quintel Blogger theme

A free Premium Blogger theme.

Showing posts with label Clearwire. Show all posts

Wednesday, November 6, 2013

3Q13 U.S. Tier 1 Carrier Results - A Conversation

I had a chance to talk to RCR Wireless' Dan Meyer on Tier 1 third quarter carrier results.

Read it at RCR Wireless here:: AT&T & Verizon Wireless

View it:


Read it at RCR Wireless here: Sprint and T-Mobile 

View it:

Sunday, July 14, 2013

Bullet Point Analysis: The AT&T-Leap Buyout


What is it?


AT&T is buying prepaid player Leap Wireless for $15 per share in cash. Under the terms of the agreement, AT&T will acquire all of Leap’s stock and wireless properties, including licenses, network assets, retail stores and approximately 5 million subscribers. AT&T expects the transaction to complete in 6-9 months (1H 2014).

What is in it for Leap?


  • For shareholders and management, they can exit the cut throat prepaid business with money. Leap and similar regional prepaid player, MetroPCS, had once enjoyed strong growth until a couple of years ago. National competitors and prepaid MVNOs ate into their marketshare and growth. T-Mobile's acquisition of MetroPCS that closed in May 2013 logically put a brighter spot light on Leap. 
  • For Leap operations, the Cricket brand expands its geographical reach beyond Leap's limited regional footprint and can go head-to-head against MetroPCS and can tap into AT&T's distribution resources.
  • For the Leap network, it has a clearer LTE path. Operating CDMA (96M POPs) and LTE (21M POPs) in the same limited AWS spectrum bands doesn't work well.   

What is in it for AT&T?


Spectrum:  

  • Complementary PCS and AWS bands covering 137M POPs, some of AWS is not in service (41M POPs).
  • Proceeds from the Leap 700 A Block spectrum goes into the deal calculus.


Subscribers and Doors: 
  • Leap has 5 million prepaid subscribers but the company has been trying to right itself after steady customer losses that began in Q2 2012. AT&T increases its prepaid customer base to roughly 12 million, roughly 11% of the AT&T total subscriber base.
  • Leap's distribution channel numbers a little less than 9,000 doors.  
  • Commentary: Leap's business needs a turnaround that Leap's management has been trying to accomplish for more than a year. In that time, Leap lost about 900K customers. Leap's distribution also slimmed down from over 11K doors in a bid to focus customer acquisition.  AT&T's own branded prepaid is not growing. The launch of the Aio brand in May allows for the company to enter the prepaid market aggressively without diminishing the AT&T brand. Now that Leap joins the AT&T prepaid fight, the strategy is shaping up to match the segmentation strategy pioneered by Sprint (Boost, Virgin, Assurance) and Tracfone (Tracfone, StraightTalk, Net10, Simple Mobile, PagePlus, and Safelink). T-Mobile also joins in the prepaid segmentation fight with its own GoSmart and MetroPCS).  All this Tier-1 competition and the plethora of MVNOs out there vying for the prepaid share of wallet will make for thin margins.  
Strategic Positioning:

Keeping T-Mobile Away: There are many who say this is a spectrum deal. That is true that additional PCS and AWS spectrum enhances the AT&T network, I argue that a large element is to neutralize a growing T-Mobile threat. Fresh off the May close of MetroPCS, T-Mobile supplemented its AWS spectrum with a $308M deal with US Cellular at the end of June.  
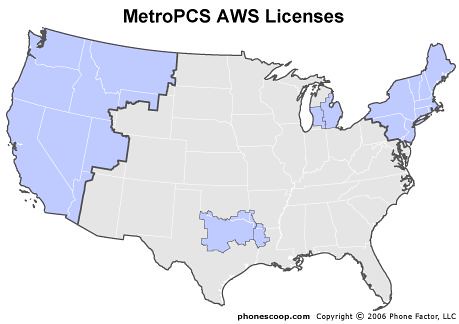
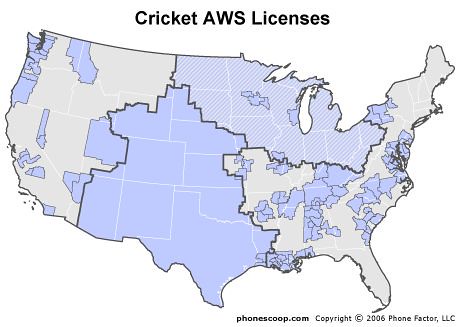
    To understand it roughly, rewind back to the ongoing speculation that a then independent MetroPCS and Leap were a perfect fit since both had the same prepaid business models and did not compete against each other for the most part. The results of the 2006 AWS auction (see graphics below) helped fuel this speculation as the AWS  MetroPCS and Leap spectrum fit provided an uncannily perfectly complement. Time has passed and some AWS licenses changed hands. 


      Graphics from Phonescoop.com
      But with the AT&T-T-Mobile merger breakup, T-Mobile received some AWS licenses and in 2012, Leap and T-Mobile traded some licenses. While the T-Mobile-MetroPCS coverage map looks empty in some areas of the country, that is not to say that the company lacks spectrum in those areas. 
      As seen in the spectrum holdings graphic, the company does indeed have spectrum nationally and can expand if so desired.  


      With the June purchase of Mississippi Valley AWS spectrum from US Cellular (Barat) Wireless) and a future rumored purchase of Leap, the T-Mobile AWS portfolio would be formidable. Aside from T-Mobile, archrival Verizon Wireless' SpectrumCo AWS deal completed in August 2012 and building out this AWS to add LTE network capacity.  


      This competitive landscape would put AT&T in an AWS coverage disadvantage relative to T-Mobile and Verizon Wireless. Therefore, AT&T needed to stay in the AWS LTE game and keep T-Mobile from growing a stronger AWS portfolio. For AT&T, AWS will not only to serve to add LTE capacity customers but also tap into future AWS LTE roaming revenue. T-Mobile, AT&T and Verizon Wireless are logical future roaming partners.  


      Which companies will feel the most impact?

      • For T-Mobile, with Leap as a unit of AT&T, its MetroPCS geographic expansion will be challenged by AT&T's resources.  T-Mobile seemingly has a year or two lead as it is integrating MetroPCS and working on migrating the CDMA base to HSPA+/LTE but the stated goal of 2015.
      • Sprint will lose 3G data wholesale revenue from the agreement forged in August 2010 that expires in Dec 2015. But now Sprint (Clearwire's owner) loses another wholesale arrangement that Clearwire announced in March 2012 though nothing really started.  It's clear now that Sprint's prepaid segmentation strategy was the correct in the long run but Aio Wireless and Cricket are going up against Virgin, Boost, Assurance, respectively. Cricket's logical national (or specific target market) expansion may spell trouble. 
      • Verizon Wireless now sees a stronger AT&T rival with new found AWS and PCS spectrum from Leap. In the long term, it needs additional spectrum to thwart impending capacity brought on with WCS and Channel 55 (700 from Qualcomm) frequencies. In terms of prepaid, its branded prepaid is holding its own but without any flanker brands, competitors will take almost all the future prepaid growth.
      • In infrastructure, AT&T LTE equipment suppliers, Alcatel and Ericsson now have more of an order pipeline than before.

      Last Word

      • The biggest question in this deal is whether the acquisition will pass regulatory hurdles. The sting of the failure to acquire T-Mobile is still fresh in everyone's minds. Like any major deal, it should have been gamed out by M&A internal and external resources taking into account the regulatory environment before it makes the light of day. 
      • If regulatory hurdles are overcome, what conditions will there be? AT&T has proactively said that the Chicago 700 MHz A Block will be sold. (It doesn't like the A block anyway). Will the company need to divest in other markets (planned or unplanned)? 

      Thursday, June 27, 2013

      DISH Folds & Some DISH Options

      Poker 

      As the long multi-hand poker game with Sprint, DISH, Softbank and Clearwire dragged on with DISH upping the ante, forcing Sprint and Softbank to push, DISH folded on both deals in the end.

      DISH's game to takeover Sprint ended on June 18, 2013 when they withdrew their offer. The press release language implied that they will devote their resources to win Clearwire. It didn't look bad when the Clearwire board recommended DISH's offer back on June 12. 
      But with a higher Sprint offer on June 20, the coup de grace came several days later on June 24 when the Clearwire board reversed its DISH recommendation for Sprint's offer.  


      DISH folded on its second poker hand with yesterday's June 26 announcement. Many including me, expected another run, upping the ante, given DISH's playing profile but what did it have to gain? Really - nothing.

      DISH's Options

      The near term scenario is that DISH needs to get service up and running. Any time you're delayed means lost future revenue opportunity. With its core business slipping, there is urgency to get into the mobile space. Given this line of thought, it needs to bury the hatchet with Sprint and move to spectrum hosting.

      A long term scenario is that DISH can wait until an alternate hosting provider comes on line. T-Mobile has been bandied about as that partner.  But why not Verizon Wireless and AT&T? Everyone wants access to new spectrum and if the deal is right, anything is possible. 

      Regardless of scenario, DISH and a partner(s) need to seed the mobile ecosystem on DISH's bands. Technically, it may not be a stretch. However, the lead times to quickly  create/productize the chipsets and integrate into production hardware (device and infrastructure) are still an issue. Once it joins the mobile service provider club, DISH can upsell its own customers on mobile broadband (either fixed or mobile) and wholesale its capacity.  

      Looking ahead, DISH is looking for another game but it may not be poker. 


      Friday, June 21, 2013

      The Finish Line is Close for Sprint

      No one expected the level of drama and the maneuverings among Sprint, Clearwire, Softbank and DISH. To be sure, the stakes were high for all parties. A poker game analogy is appropriate as this corporate soap opera has seen its share of raised bids and stare downs.


      DISH with Charlie Ergen at its helm played the classical disruptor, raising the stakes on its bid on both Sprint and Clearwire. It's logical since the DISH core business is sliding and DISH has no access to any mobile opportunities (revenue).  Though DISH has its own spectrum, it doesn't have the ability to launch service on its own. With Sprint's Network Vision strategy, DISH can ride the Sprint host with lower capital expenditure than if it built a network from scratch. But Sprint has a revenue generating subscriber base and direct sales channels that DISH can tap into if it own Sprint.  However, with a deeper pocketed Softbank raising the ante, DISH needed to fold and focus on a less capital intensive deal - Clearwire.

      However, Sprint "pulled a DISH" and raised its bid for Clearwire at the last minute $5/share vs $4.40.  This reversed a Clearwire board recommendation for DISH. Let's face it, money talks and with that, the activist investors were placated. After all, they were looking to maximize any bid anyway. What didn't hurt was Sprint's lawsuit against DISH and Clearwire citing the illegality of the DISH offer.   Sprint is near the finish line to realize 100% ownership of Clearwire, unless DISH "pulls another DISH." 

      The real question if the Sprint-Clearwire deal makes it is what are DISH's options to get into the mobile space and monetize its spectrum? Will Sprint and DISH bury the hatchet? In my view, they have to. DISH still needs to make use of its spectrum and Sprint is the logical partner (at this moment) since Network Vision was created for spectrum hosting. Though Sprint said in the past, wholesale revenue wasn't totally baked into the Network Vision model, any wholesale money (a fleeting LightSquared) will help its return on investment. Of course DISH can court T-Mobile, but they're focusing on its own LTE buildout. Moreover, they haven't planned for spectrum hosting. We shall see............. 


      Monday, December 17, 2012

      Sprint and Clearwire - It had to be - Network Future?

      Now that Sprint will acquire the remaining 50% of Clearwire that it already did not own, what does this say about the near term and future?  While there are many stories about the financial side, most industry insiders knew that the Clearwire acquisition was a strategic imperative. Back in October when Sprint moved to take more control, I offered some thoughts  on why Sprint's long term control of Clearwire made sense. Much of the logic is rooted in the long term network strategy.

      Network Vision

      Sprint's network strategy hasn't changed since 2010 with the introduction of its Network Vision.  Many analysts derided the price tag and its hosting positioning but today, Sprint's bet seems to have turned out well.

      When Sprint announced Network Vision in 2010, it seemed a bit presumptuous that 2.5 GHz was included into the spectrum chart especially since Clearwire had not committed to the effort and especially Sprint did not control any of that spectrum.  Clearwire had its own separate network deployment strategy with capital already sunk in specific markets using WiMAX to power Sprint's 4G data play. 


      In order to expand markets, it was logical that Clearwire take advantage of Network Vision but that didn't happen. Executive tensions (between Sprint and Clearwire), the need for Clearwire corporate independence and lack of capital to expand contributed to stalling the grand Network Vision execution.  With the urgency to stay in the LTE game against wireless competitors, Sprint worked with Clearwire on specific markets to deploy the TD-LTE flavor in specific 'high data tonnage' markets.  It was clear, Clearwire would provide the complement to Sprint's near term PCS-based LTE strategy.  

      Fast forward to 2012, what has changed?  The answer - Softbank.  Though the Softbank-Sprint acquisition approval is scheduled for mid-2013, Softbank's $3.1B bond purchase in October freed Sprint to make specific strategic moves beyond Clearwire in the form of US Cellular subscriber and spectrum acquisition in November. 

      Back to the 'new' Sprint network,  surprisingly, the network slide hasn't changed.  To Sprint's credit, they're executing on their vision.


      But what has changed is a bit more detail specific to LTE.  Today's 800 MHz band primary is envisioned for voice. With better in-building penetration properties, having voice is still the 'bread and butter' revenue bearing service.  800 also hosts the soon to be discontinued iDEN platform. Eventually 800 will also run LTE with VoLTE.  However, 800 LTE is more than 2-3 years away. The near term LTE solution is in the PCS band. But with only a 5 X 5 deployment and also running 3G, the analyst community questioned whether this could handle increasingly high-data usage especially in light of an unlimited data service proposition. 

      Enter TD-LTE and Clearwire

      To address high data use, Sprint engaged Clearwire in a data offload arrangement.  Rather than a national TD-LTE view, Sprint would identify specific high-data tonnage markets for Clearwire to buildout its TD-LTE. The concept: with plenty of 2.5 GHz spectrum, Clearwire (and Sprint) could address subscriber [retail and wholesale (think data MVNOs)] capacity and still offer a speed differentiation. Yet with an independent Clearwire, Sprint clearly had no control of its future. Therefore, it was a strategic imperative for Sprint to take over Clearwire.   Sprint also had to act as the financial community was advocating Clearwire sell "excess" 2.5 spectrum to raise cash.  This flies in the face of any network planner as history has shown that spectrum always appreciates and the overused 'spectrum is the lifeblood of a network' adage still holds.

      Two "2.5 GHz Dollar" Questions 

      Assuming that the Clearwire acquisition goes through, will Sprint expand or accelerate the original Clearwire deployment plan?  I say yes, they have to eventually.  Whatever the TD-LTE markets previously agreed upon, it only address specific high density markets.  To offer a broader coverage story that rivals competitors, Sprint will need to show a bigger TD-LTE footprint.  It's taken for granted that a data-offload (of PCS LTE) strategy is still in play.  

      There are two questions in my mind that Sprint need to address.  First, a broader future question is when Sprint will exploit the national 2.5 GHz coverage.  With a national footprint, Sprint ensures a richer wholesale platform and deeper capacity.  Sprint strategy guys have likely played this scenario out.  With less than ideal propagation (relative to 800 (and 700)), small cells and associated backhaul will play a prominent role (read more capital).  The second is more of a technical question.  When will Sprint take advantage of its potential speed advantage. With aggregating spectrum, Sprint can position speed and unlimited as a marketing differentiator much like Verizon Wireless' coverage.  Of course the answer is when the TD-LTE ecosystem commercially supports this on the infrastructure and device side.

      Stay tuned for more Sprint moves in 2013. 

      Thursday, October 25, 2012

      A Clearwire Graphic

      While looking for some Clearwire Q3 Earnings material, this graphic nicely popped up.  It's clear that Clearwire is punctuating its vast national spectrum versus the tier one carriers.

      For those who are curious:
      • Operator A is Verizon Wireless
      • Operator B is AT&T
      • Operator C is T-Mobile 
      • Operator D is Sprint
      Looking ahead for roaming:

      • AWS LTE stands to be a major roaming frequency with Verizon Wireless and T-Mobile in control.
      • PCS LTE roaming should eventually happen. Sprint is the early adopter out of the gate.
      • Cellular 800/850 LTE - big question mark on what will be when AT&T and Verizon Wireless refarms.


      Wednesday, October 24, 2012

      Sprint - Thoughts Ahead of the Earnings Release


      Sprint is the third Tier 1 carrier set to release its earnings and performance metrics, October 25th at 9:00 AM.   The company is in the midst of a turnaround cycle. For the most part, it is succeeding as evidenced by customer service, churn decline and postpaid growth (on the Sprint platform). This turnaround story is in part what drew the October 15th SoftBank $20 billion acquisition.  While the deal isn't expected to close until next year, Sprint ahead of this earnings call has moved to acquire controlling interest in Clearwire as a foundation for the 'new' Sprint's future plans. Regardless of the good news for Sprint, its meat and potatoes operations either support its continued the turnaround trend or present areas of challenge.

      Net Additions:   

      On a macro view, the overall net additions are in the positive range largely due to the strength of Sprint's prepaid strategy and wholesale business. The number of MVNOs using the Sprint platform has been a welcomed component in driving net additions.   On the postpaid side, there are two stories that newcomers need to focus on.  One is the iDEN side which has been bleeding subscribers for a couple of years. There's no secret that the iDEN network will cease in mid-2013, the thrust is to retain the remaining 4.4 million iDEN (as of Q2 2012) customers of which 3.1 million are postpaid. It stands to reason that the remaining iDEN subscribers are a loyal base that depend on the push to talk function and have it well integrated in its operations.  They're the candidates to migrate to the CDMA-based Direct Connect. However, Verizon Wireless and AT&T has been very aggressive in courting these customers throughout the years. In Q2, Sprint presented a 60% iDEN subscriber recapture rate, the expectation should be that percentage should increase.  iDEN losses amounted to under one million in Q2 of which over two-thirds were postpaid. Sprint has warned that these losses will pick up towards iDEN's end of life.  What will Q3 hold in total iDEN losses and most importantly, the recapture message?

      It's clear that the Sprint platform (a mix of CDMA and now LTE) will continue to be positive.  The upswing in its Q2 442K postpaid net additions were largely helped by the 1.5 million iPhone gross adds which brought in switchers (40% new to Sprint).  Observers will continue to pay attention to the iPhone numbers that should manifest itself partly in churn and postpaid net adds.  With its unlimited proposition and a Sprint LTE iPhone, will 40% stay flat or increase?  


      On the prepaid front, the Assurance growth engine (as well as other companies with similar offerings like Tracfone's Safelink) had been impacted with the FCC's modernizing of the Lifeline program in Q2. Will this continue to impact Q3 results? A big bet in prepaid was the introduction of the iPhone at Virgin Mobile. However Sprint did not provide the granularity of prepaid versus postpaid iPhone activations.   It'd be nice to understand the Boost and Virgin Mobile brand's contribution to the prepaid story.

      Churn:   From a trend view, Sprint is definitely turning around. Though the postpaid figures incorporate the iDEN bleeding, the results have been good.  For the Sprint platform (Q2 1.69%, Q1 2.0%), it has offset iDEN figures well (Q2 2.56%, Q1 2.09%). To follow a turnaround story that incorporates the anti-churn tool (iPhone), one hopes that the Sprint platform percentage to continue to decline.  Will it break 1.5%?  


      Similarly on the prepaid side, the trend looks decent but detail needs to be examined on the Sprint platform figures for Q3. As a reference gauge with Q2/Q1 numbers, Sprint platform reported 3.16%/2.92% while the iDEN side came in with 7.18%/8.73%.  Prepaid churn is tough as it's the nature of the offering but sticky products and decreased trending help the cause.

      ARPU: Sprint 's approximately $61 postpaid ARPU mark follows only AT&T. With AT&T just increasing to $65.20 in Q3, The expectation for Sprint is to cross $61 given Sprint's sharp growth slope.  

      Prepaid ARPU (Q2 - $26.59/ Q1 $26.82) is trending down partly as the result of possible dilution associated with lower ARPU bearing Assurance customers. Logically, as those customers increase in number, it offsets the higher-ARPU bearing Boost and Virgin Mobile Beyond Talk subscribers. However, Sprint executives have always touted the low-churn aspect of Assurance users along with low acquisition costs. Therefore, they argue, Assurance users are provide stable profit in the long term.  

      Monday, October 22, 2012

      Carrier WiFi Offload - Some Thoughts - Part 2

      In Part 1, Verizon Wireless and AT&T were discussed. To summarize, AT&T has good depth in hotspot/hotzone assets that formulate their WiFi data offload strategy.  Verizon Wireless on the other hand does not have any assets and currently partners in a white label fashion with Boingo to offer WiFi access as a benefit for mobile broadband customers. Therefore, Verizon Wireless does not really have a WiFi offload strategy (aside from some stadium/convention center WiFi buildouts to save its cellular network).  That can change possibly with a potential CableWiFi partnership.Now onto the other Tier 1 carriers.

      Sprint: Sprint currently doesn't have a WiFi offload strategy. They do not own any WiFi assets and like many carriers, encourage their subscribers to use WiFi with the smartphone WiFi feature.  Sprint got out of the WiFi game in 2007 with the sale of some airport assets to Boingo. Given that one would expect a WiFi relationship like Verizon Wireless'.


      Yet Sprint's unlimited data proposition, its background Clearwire WiMAX flate-rate wholesale deal, and tenuous financial state at the time may have negated a need for a WiFi partner. Going forward, it remains to be seen if WiFi is a necessary strategy component given the pending SoftBank deal and Sprint's majority control of Clearwire (use more 2.5 GHz bandwidth for capacity and speed).  It now for the most part has owners economics in furthering the unlimited data proposition. Aside from the broader Network Vision sites, small cells and/or distributed antenna systems are likely going to be deployed to help with meeting subscriber capacity issues. Nevertheless, the wild card is Boingo and its strategic WiFi provider partnership with the Competitive Carrier Association or CCA (which Sprint is a member).

      T-Mobile: Similar to AT&T, this carrier owns its share of WiFi hotspots.  Though the numbers are much smaller, they do at least provide a wholesale and direct to subscriber revenue opportunities. T-Mobile's WiFi strategy foundation was also based on supplementing the lack of cellular coverage and then building services such as Unlimited Hotspot Calling and Hotspot@Home.   

      Unlimited Hotspot calling also addressed adding additional calling minutes. Not that it makes a difference today, a WiFi calling feature is a popular feature for globetrotters as a free alternative to paying for global voice roaming rates, provided there is WiFi access. 

      When AT&T purchased Waypoint, it grabbed the Starbucks contract from T-Mobile. But as anyone knows who frequents that coffee chain, the WiFi is free and clear.  T-Mobile still has WiFi presence in airports and hotels. Some can argue that it provides a dual benefit. The direct to consumer WiFi allows for the company to opportunistically address the tablet/laptop user who must have a WiFi connection. With hourly, weekly or monthly plans (and global roaming), T-Mobile no doubt eeks out some revenue from this line of business.  With this and the lack of substantial WiFi hotspot assets, carrier offload is not a the core of its WiFi strategy.  As with Sprint, Boingo is a wildcard for T-Mobile (as a member of CCA) to embrace since.   

      As stated, Boingo is a possible resource to tap for carriers to expand a WiFi offering but Boingo is a WiFi aggregator (cobbling smaller players like hotels, motels, RV campgrounds, independent coffee shops, etc.) with limited WiFi assets (mostly in airports). The issue for Boingo is how they can bring substantial domestic WiFi hotspots to the table without outlaying any CapEx.  


      Friday, October 19, 2012

      Carrier WiFi Offload - Some Thoughts - Part 1

      It's well known that WiFi plays an important role in mobile data consumption.  From the consumer view, it's faster than 3G (and maybe 4G in some cases), it's usually free, and it's seemingly ubiquitous.  

      From the carrier view, any subscriber getting off the cellular data network helps capacity and saves on the customer's data caps, if any.  Some carriers can argue that open WiFi is not secure and worried about possible liabilities of customers throwing their data 'in the clear' on unsecured networks.
      Given the differing carrier stances, here is where I see carriers' WiFi strategies. 

      AT&T: Before the company bought Wayport in 2008,  it boosted its hotspot count.  Since then, AT&T has been reinforcing its national leadership in WiFi hotspots. AT&T smartphone and mobile broadband customers get the benefit of automatically connecting into AT&T hotspots or HotZones.  Their nice (and proprietary) smartphone client does this seamlessly without the customer needing to hunt for the correct SSID.  In this instance, it's a win-win. Customers get a seamless fast experience and AT&T offloads the data traffic.  It continues to invest in this technology with more and more hotspots deployed monthly, quarterly, annually.  So AT&T's WiFi strategy is to own the assets and in directly monetize through customer subscriptions.   

      Verizon Wireless/Verizon: Verizon has never really warmed up to WiFi in the cellular network. These statements were made in the 3G deployment era and have continued as the corporate position when executives are asked about their WiFi strategy.  On the surface, it appears Verizon Wireless' WiFi strategy is not to have one.  However, a little known fact is that they indeed have a relationship with Boingo albeit a white label one.  Boingo powers both Verizon fixed line as well as the wireless business unit.   Unlink AT&T, only mobile broadband and specific fixed hi-speed internet (e.g., FiOS) customers are eligible.  Smartphone customers cannot take advantage.  But that may soon change with the introduction of CableWiFi in May 2012.


      Cable is my Frenemy:

      Cable companies have always been aligned with Sprint but with missteps on Clearwire, cable wireless retail strategy (Pivot), the relationship ended.  In 2006, cable companies' AWS spectrum foray (a.k.a. SpectrumCo) also included Sprint. But Sprint got out of SpectrumCo in 2007 cashing out its share. Fast forward to August 2012.  The FCC approved the sale of the former SpectrumCo AWS portfolio to Verizon Wireless.  Verizon Wireless and the cable companies are friends. Verizon Communications (fixed line) are enemies. All this closeness opens up the possibility that Verizon Wireless will use CableWiFi coverage to address data offload and will be Verizon Wireless' WiFi strategy.  

      If so, Boingo is left without a dance partner.  To its credit, Boingo saw the writing on the wall and going to court members of the Competitive Carrier Association in September.  In fact, Boingo became CCA's strategic WiFi partner.

       More on other companies in the next post!

      Carrier Q3 2012 Earnings Releases

      The following are the US carrier Q3 2012 earnings release dates:


      Carrier
      Date
      Time (ET)
      Verizon
      Thu, October 18
      8:30 AM
      AT&T
      Wed, October 24
      9:00 AM
      Sprint
      Thu, October 25
      8:00 AM
      Clearwire
      Thu, October 25
      4:40 PM
      MetroPCS
      Tues, October 30
      9:00 AM
      Leap
      Wed, November 7
      11:00 AM
      T-Mobile
      Thu, November 8
      4:00 AM

      Thursday, October 18, 2012

      Why the Surprise over Sprint Controlling Clearwire?

      There are people in the media and the industry who are astounded that Sprint would enter into control of Clearwire, especially with the history of friction at the executive levels.  To be sure, Clearwire and Sprint have been on their respective rollercoasters but the relationship is symbiotic and beneficial in the long term.  
       

      Clearwire's value proposition is its spectrum depth. Though it seemed to be handicapped with the funky non-standard 2.5 GHz band and more TDD than the standard FDD, this has turned around for the better.  What's good?

      • The spectrum depth allows Sprint to continue to offer an unlimited proposition. It does so now using WiMAX technology under a flat-rate contract with Clearwire. When TD-LTE comes, the current thinking is to address 'high tonnage' markets for data offloading from the Sprint 5 X 5 channel PCS LTE network.
      • Having TDD spectrum can be advantageous. You can devote more channels to the downlink. Most of the data consumption is on the downlink anyway whether it's mobile or fixed.  Under a FDD scenario, the bands are usually the same 'width.'  If there isn't a lot of uplink traffic, it feels like it's less efficient.  
      • That funky band (sometimes a little variation - 2.6 GHz (close)) is now positioned to be a global LTE roaming band with presence in Asia and Europe.
      If purchasing Clearwire wasn't an overt condition of the SoftBank deal, it should have been logical given the speed ambitions of Mr. Son. Allowing a non-fully controlled Clearwire can upset that plan.  The Clearwire takeover scenario would never have come into play with out the SoftBank acquisition. Sprint was in no financial position to further outright fund Clearwire as it was busy with its own turnaround execution.  

      Network Vision Looks Better

      Bob Azzi (Sprint's public face for Network Vision) must be relieved.  When Network Vision was conceived, it was pre-built with spectrum hosting/network sharing in mind.  Although LightSquared signed on, their business model went south due to GPS interference.  The Sprint conceived 2010 Network Vision graphic below kind of blatantly put the 2.5 GHz band out there even though Sprint didn't own the band.
      Meanwhile Clearwire was expanding on its own WiMAX network in specific markets with expansion encumbered by CapEx and customers to help with that pesky revenue thing.  Throughout Network Vision, analysts including me, expected that Clearwire would jump on board. But they didn't.  Some point to money, some point to independence but the end result is that Clearwire was not on the Sprint Network Vision bandwagon.  This may have changed as Clearwire and Sprint worked out their TD-LTE deployment priorities. Sprint desires specific markets that Clearwire had no network, the Sprint Network Vision platform would be the natural choice rather than spending the CapEx on a parallel network.

      What Could Be: If there is enough money (thanks SoftBank), Sprint and Clearwire can be more aggressive in TD-LTE expansion, going to more geographic markets than planned (constrained). Sprint's slim PCS-based LTE won't have that spectre of capacity challenged.  Moreover, more channels (and maybe hardware and backhaul and....) can be thrown to not only address capacity but also speed, addressing Mr. Son's fast mobile speed experience expectation. 

      Wednesday, October 17, 2012

      Leap LTE - Burning the Candle at All Bands

      Leap (Cricket) is comparatively a slow mover in LTE deployment. Its first market began as a test market in December 2011 in Tucson, AZ. Just today, Leap launched its second market, Las Vegas. 

      The commonality between the two announcements have been the only release device being the Huawei Boltz USB modem at $149.99 or as my analyst brethren (rounds down) say $149.  Though many carriers have traditionally launched with modems first, carriers have traditionally taken a lot of heat over the lack of other devices (yes, smartphones) at launch.  Leap follows continues the trend with more smartphones in the pipeline.   


      Service Innovation Unrecognized

      For those who follow Leap, it's perplexing why they are emphasizing mobile broadband plans as they have been de-emphasizing their 3G mobile broadband plans. Leap has been bleeding 3G mobile broadband customers for many quarters. Perhaps some of it was planned as those customers had no data caps and pounding the 3G network for relatively inexpensive price points.  Perhaps the new LTE data plans stand to be more profitable.

      $50 Plan - 5 GB @ 3 Mbps
      $60 Plan - 5 GB @ 6 Mbps

      The company doesn't get credit for its speed-dependent rates.  This model follows the fixed line internet model where one pays more for faster throughput.  Back to the modem which may appear archaic in today's WiFi hotspots like the (also Huawei) Crosswave.
      It's likely that Leap wants to control the data consumption to protect the network and customers alike.  

      Lots of Future LTE bands  

      Here is where Leap seems to be schizophrenic with its LTE strategy and burning the candle at all bands, making things complex.  These latest markets have been launched using AWS bands.  Earlier, Leap signed on with Clearwire in March 2012.  Yet there is another band in the mix - 700 MHz A Block (Chicago only).  This came about with the swap with Verizon Wireless approved in August.  So let's recap what Leap will need to support in the coming years:

      • AWS LTE
      • 700 MHz LTE (Chicago-only, what's that all about?)
      • 2.5 GHz TD-LTE 

      It's safe to say that multi-band support is giving device makers challenges but on top of this, it's safe to inject other LTE roaming band support into the mix. Still, the carrier has promised 21 million POPs covered by the end of the year. Network engineers and installation people must be frantically working.


      Verizon Wireless Thoughts Ahead of the Earnings

      Verizon Wireless is set to release its earnings and performance metrics tomorrow, October 18th at 8:30 AM. The wireless group has been a rock steady performer as evidenced by many quarters of impressive net additions and churn.    

      What to hope for this year's Q3? 

      Net Additions: Wholesale net additions have been helping out many carriers' numbers. This is a trend that should continue given emphasis on M2M.  The true test is how many new postpaid customers the carrier will bring on board. As Verizon Wireless is mainly a postpaid company and the postpaid market penetration increases, there are high expectations for the carrier to continue to crank out more customers.    


      Verizon Wireless has never gone below 500,000 postpaid net adds since Q1 2010.  With Q2 2012 delivering 888,0000 postpaid, the expectations are high. Yet a shining light has emerged since Q2 2011 for the prepaid group, turning the ship from losing subs to greatly contribute to the overall numbers.


      There are equally high expectations for Q3 from the prepaid side given the momentum over the previous quarters.

      Churn: It's like a broken record. Verizon Wireless can do no wrong in terms of churn.  Their subscriber loyalty and network messaging has proven out quarter after quarter. Any spike would be alarming. Any drop only strengthens their operations.


      ARPU (Rather - Postpaid ARPU):    Postpaid ARPU is likely to going up but the largest US carrier has a lot of catching up to AT&T and Sprint.


      This could be the quarter that Average Revenue Per Account (ARPA) gets introduced.  Executives have been on the media and investor circuit arguing that ARPU would be dated and the true indicator should be by account, given its thrust into shared data plans. 

      SoftBank & Sprint Deal - Speed Expectations & Implications

      In the October 15, 2012 Japanese Strategic Partnership announcement, SoftBank's CEO Masayoshi Son cited slow US network speed compared to Japan.  Though the chart reflects 2011 data and may change as the US builds out LTE in the coming years, the point is that Japan leads the way. Conspicuously absent, by the way, are know speed-forward countries South Korea and Singapore.


      Reading between the lines, SoftBank has lofty speed ambitions based on the Japanese market. While LTE will be the great speed equalizer in the US market stands now, competitors cannot claim overall speed dominance.  Sure AT&T and Verizon Wireless go back and forth citing 3rd parties (here and here), the reality is that carriers cannot officially state that their LTE is faster than competitors.  Part of the speed equation is capacity.  While speed brings in the early adopter speed geeks, the bigger carrier thrust is to make the data service available to everyone.  This means having sufficient capacity within spectrum constraints.

      US carriers have been providing operating expectations though. Some more specific than others.


      Verizon Wireless' latest LTE market expansion announcement alludes to speed ranges:


      "In real-world, fully loaded network environments, 4G LTE users should experience average data rates of 5 to 12 megabits per second (Mbps) on the downlink and 2 to 5 Mbps on the uplink. When customers travel outside of 4G LTE coverage areas, devices automatically connect to the Verizon Wireless 3G network, where available, enabling customers to stay connected from coast to coast."


      AT&T positions its LTE speed in comparison to 3G in its latest LTE market expansion in Dallas-Fort Worth release. 


      " Faster speeds. LTE technology is capable of delivering mobile Internet speeds up to 10 times faster than 3G. Customers can stream, download, upload and game faster than ever before."

      Interestingly, rather than stating a range, it pits it has superior LTE speed against Verizon Wireless citing a PC World comparison (here). 


      Now back to Sprint.  As it builds out its Network Vision strategy, its LTE implementation is a rather small 5X5 MHz channel implementation. Smaller channels and balancing capacity may yield slower speeds but that doesn't stop its marketing.


      Looking ahead when Clearwire comes into the picture with their TD-LTE technology, the current Sprint view is for data offload in 'heavy data tonnage' markets. This suggests a capacity approach given Sprint's unlimited data proposition.  Yet Clearwire's spectrum depth also allows Sprint to add the additional speed component, thereby realizing Son's vision of blowing the doors off competitors (in Japan and the US).  If speed (along with unlimited) is going to be a market differentiation, Clearwire and network expansion and tweaks will be necessary in the coming years.  This means more capital is necessary for Clearwire to do so.  Direction and commitment will be necessary from the 'new' Sprint.